Pictures and figures on this page are for illustration only. They're here to show what damage can look like, and why having a correct replacement value on your property matters.
What could a repair cost you?
Indicative only.This is not a valuation, quote or financial advice.
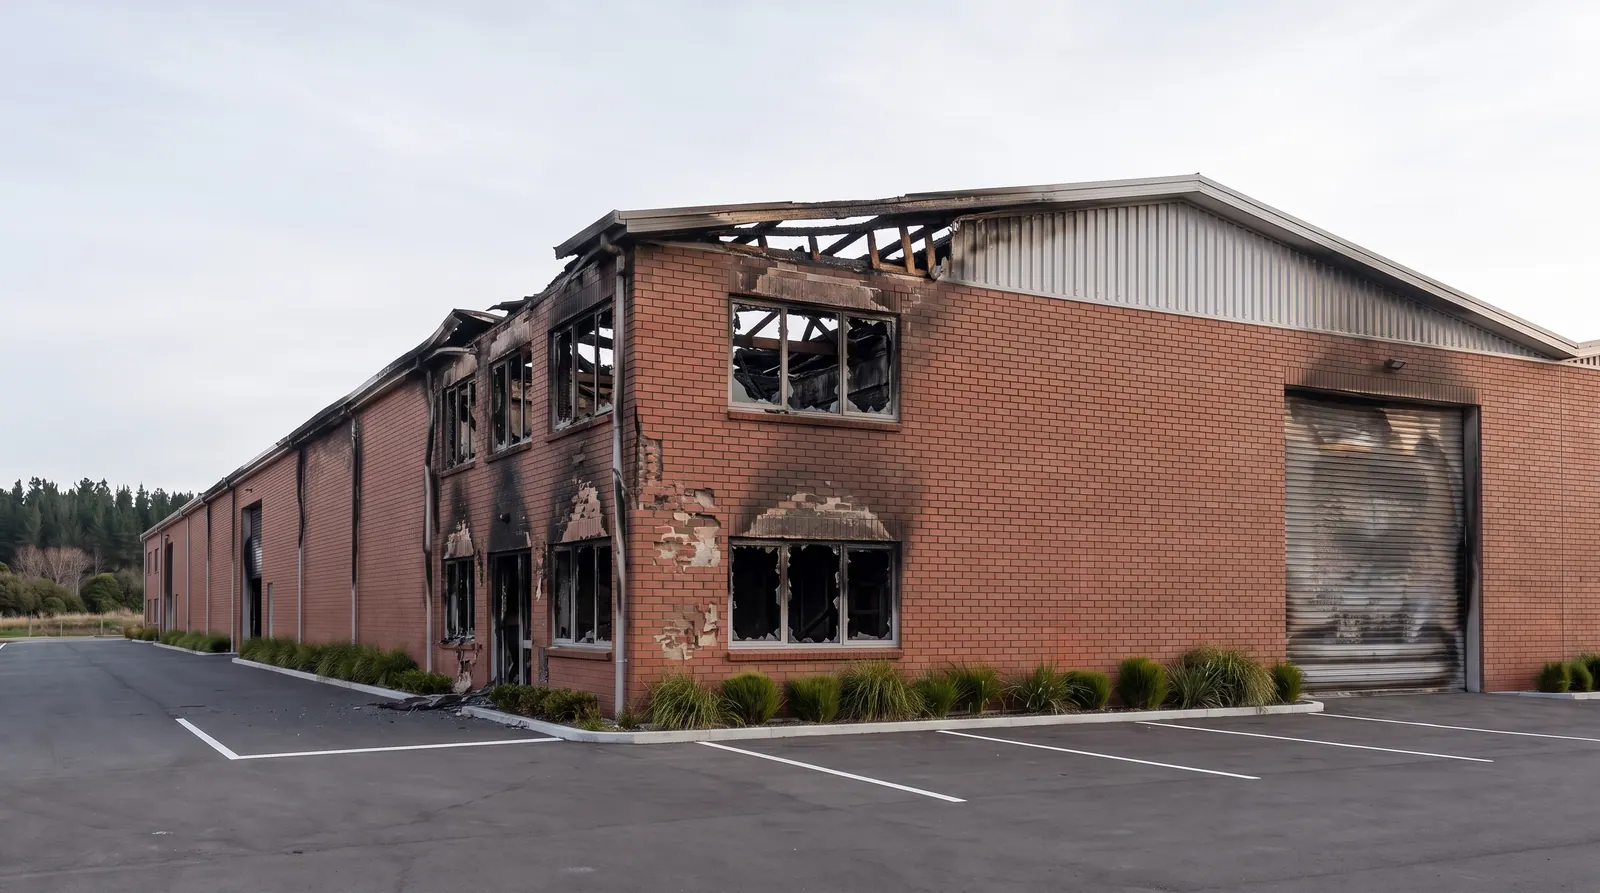
Estimated cost of repairing the damage shown, excluding GST.
How this was calculated
$2,350/m² (Industrial / warehouse) × 1.00 (Hawke's Bay regional cost index, estimated) × 1.04 (Brick veneer) × 1.03 (cost movement since the published rates) × 1,200 m² = $3.02M to rebuild in full.
That figure × 40% (the fire damage curve at 45% of the building affected) gives a midpoint of $1.21M. The range shown runs from 20% below to 25% above it, and never above the full rebuild cost. Figures are rounded to three significant figures.
What the figure covers: building work, professional fees, a contingency, and the site works and strip-out that a repair involves. It excludes GST, plant and stock, and cost increases during the rebuild. Demolishing and clearing an entire building after a total loss is a separate cost again, and a sum insured has to carry it.
The industrial rate assumes a typical modern building with a normal office or amenity area. A warehouse with very little office space may come in lower; one with a large or high-spec office may run higher.
Rates come from Rider Levett Bucknall's New Zealand Riders Digest 2025, with an allowance of 20% for fees, site works and contingency, brought up to date with Stats NZ's capital goods price index. Hawke's Bay isn't in the published regional index, so it is held level with Auckland rather than estimated below it. Where the data leaves room for judgement we estimate on the high side: being over costs you nothing, being under is how buildings end up underinsured.
The 80% point at which a repair is treated as a likely total loss is a general insurance rule of thumb, not a fixed Insurance Collective policy. Every real claim is assessed on its own facts. The pictures are illustrations of the kind of damage described — not a real building, real location, or real values, and not a prediction of any particular loss.
Questions about your cover? Call 027 213 4362.