Landlord Insurance
Cover built for rental property, including tenant damage, lost rent and meth contamination.
A rental property is a business asset, and standard house insurance is not written for one. House policies assume the owner lives there, so the risks that actually cost landlords money - damage caused by a tenant, rent that stops coming in, methamphetamine contamination - are commonly excluded or capped. Landlord insurance is the cover that fills those gaps, and the limits and conditions vary a great deal between insurers.
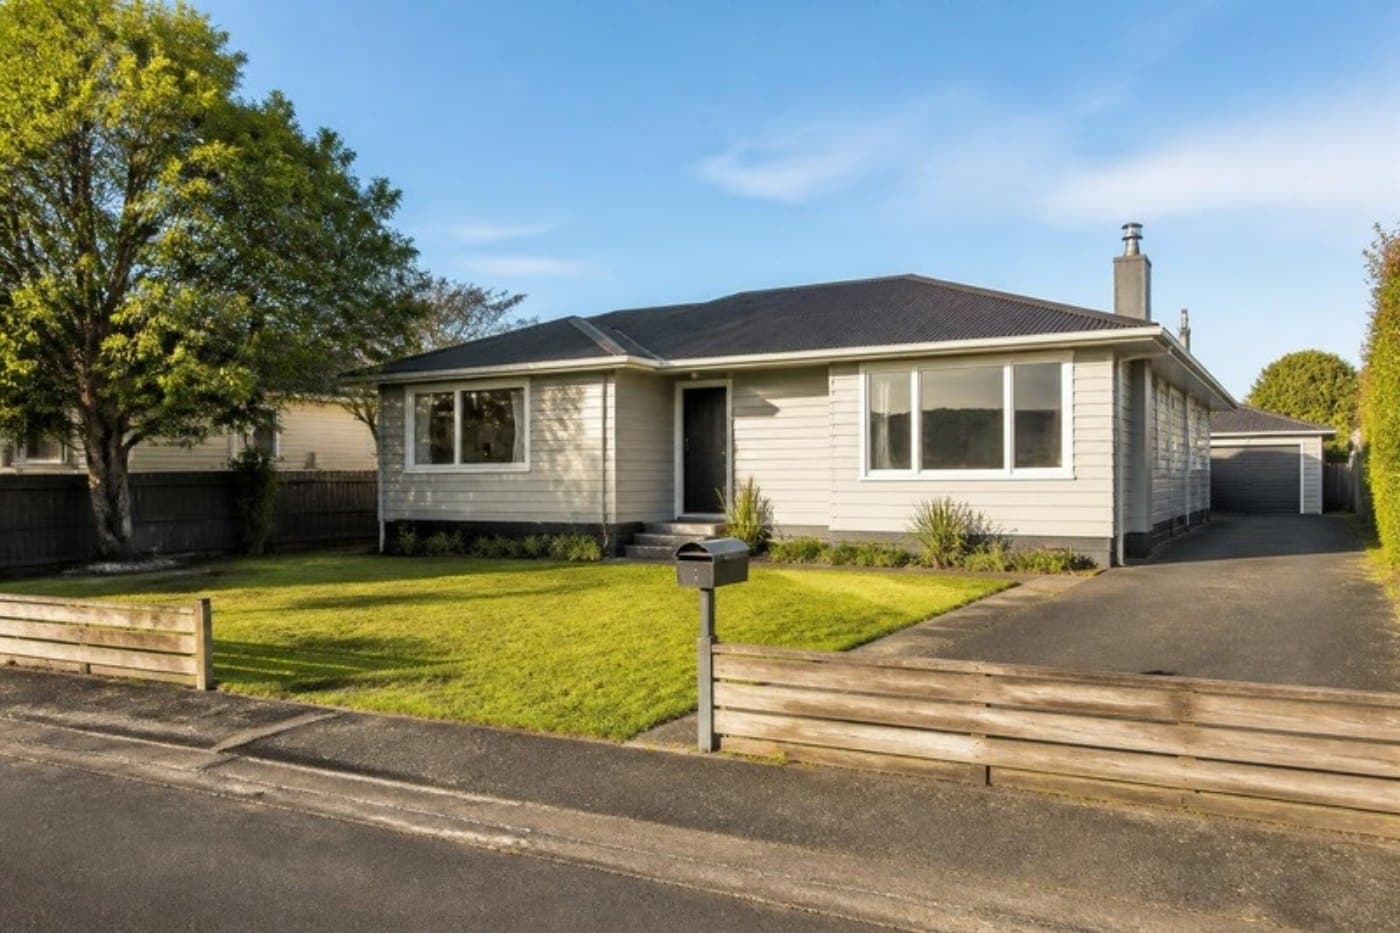
Landlord Insurance- what's included
- The building, fixtures, fittings and any chattels you own
- Deliberate or malicious damage caused by tenants or their guests
- Loss of rent while the property is uninhabitable after an insured event
- Rent default cover, where a tenant stops paying
- Methamphetamine contamination, testing and decontamination
- Landlord liability for injury or damage connected to the property
Who it's for
Residential rental property owners, from a single rental to a portfolio - including trusts, and owners who hold commercial and residential property side by side.
Why us
Why arrange it through The Insurance Collective
Genuinely local
Hawke's Bay brokers who know the region and can meet in person.
An advocate at claim time
We negotiate the wording and fight for a fair outcome when it counts.
National buying power
Insurance Advisernet membership means access to every major insurer.
Talk to a real person
“When something goes wrong, you won't reach a call centre - you'll reach one of us - someone who already knows you and your cover. That's the whole point of doing this properly.”
Ryan
027 545 0908Frequently asked questions
Isn't my house insurance enough if I rent the property out?
What does loss of rent actually cover?
How does meth contamination cover work?
Does it cover damage the tenant caused on purpose?
What does landlord insurance cost in New Zealand?
Can you arrange cover for a portfolio or a trust?
Do you charge for a quote?
How much will it cost?
How quickly can you arrange cover?
What areas do you cover?
What happens if I need to claim?
Related cover
All solutions- Commercial Property InsuranceCover for commercial buildings and portfolios with market-leading wordings and excess options.
- Body Corporate InsuranceShared-building cover arranged for the body corporate, its common property and owners.
- Goods in Transit InsuranceCovers your stock, materials and equipment against loss or damage while they're being moved.
Worth reading
Plain-English guides related to landlord insurance.
Ready when you are
Get a quote for landlord insurance
Tell us a little about your situation and we'll come back with a personalised quote and straight-talking advice.
or Contact us
- Free & no obligation
- Insurance Advisernet member